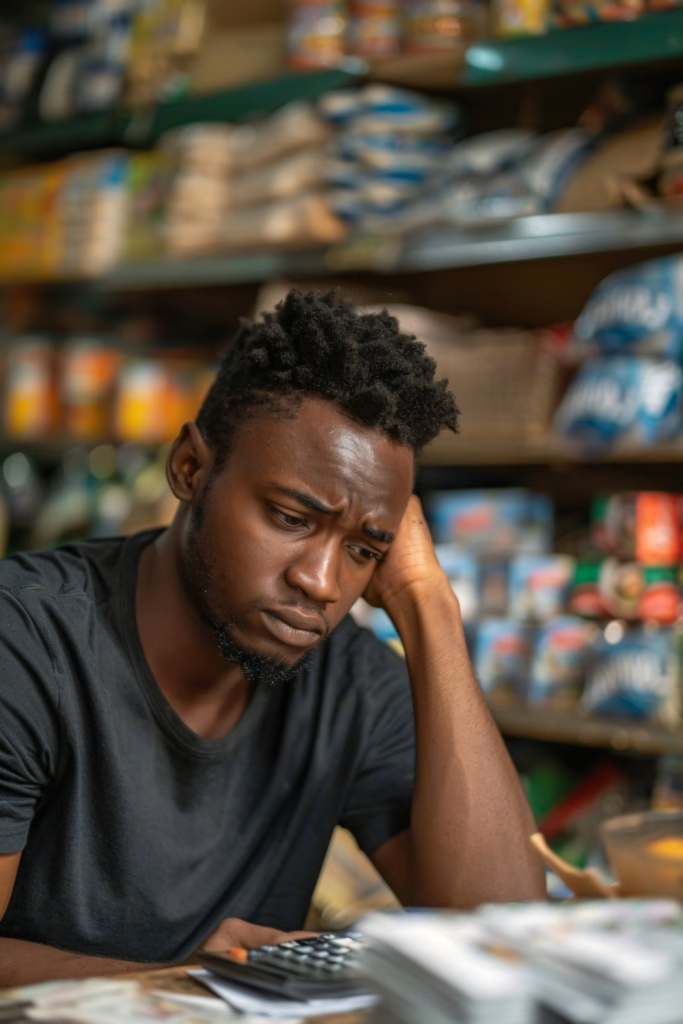
Payday feels like a celebration. You check your bank account, see the deposit, and for a moment, everything seems possible. But then, by the middle of the month—or even before the next pay comes—you start feeling broke again. You ask yourself, “Where did all my money go?” This scenario is far more common than most people realize. Feeling broke even after getting paid isn’t about your income. It’s about how your money flows and how habits, decisions, and mindset shape your financial reality.
This article explores why so many people struggle to feel financially secure, even with a steady income. We’ll dive into spending habits, money psychology, and practical ways to change the cycle so your paycheck lasts longer and your money works for you.
The Paycheck-to-Paycheck Trap
Living paycheck to paycheck is a term that describes using your income just to cover immediate expenses. Rent, bills, groceries, and other costs take up nearly everything, leaving almost nothing for savings or investments.
Even if your paycheck seems “enough,” rising costs, unexpected expenses, and poor financial planning can leave you feeling broke. Many people fall into this trap without even realizing it. They earn, they spend, and then the cycle repeats. Breaking free requires understanding exactly where your money goes and taking control before the next payday arrives.
Why Budgeting Alone Isn’t Enough
Budgeting is essential, but many people do it wrong—or only partially. A budget isn’t just a list of expenses; it’s a strategic plan to ensure your money covers your needs, builds savings, and grows your financial future.
Problems arise when people forget to account for irregular or hidden expenses, like gifts, transportation surges, subscription services, or small daily purchases. Overlooking these costs makes your money disappear faster than expected. Budgeting should be realistic, adaptable, and precise. Every cedi should have a purpose, whether it’s for essentials, savings, or fun. Without a complete picture, your paycheck will vanish, leaving you frustrated and broke-feeling.
Spending Without Awareness
Many people spend money automatically, without realizing the cumulative impact. Daily coffee runs, small snacks, impulse purchases, or quick online buys may seem harmless, but over time, they add up.
When your spending is unconscious, your money doesn’t last, no matter how big your paycheck is. Tracking your money and observing your patterns is the first step to breaking this cycle. Simple apps, a notebook, or digital spreadsheets can help you see exactly where your money goes. Awareness turns spending from random to deliberate, allowing you to stretch your paycheck further.
Lifestyle Inflation and Why It Hurts
Lifestyle inflation happens when your spending increases as your income rises. You get a raise, so you buy a better phone, eat out more, or upgrade your wardrobe. The problem is that while your income rises, your expenses rise too, often faster than your financial goals can catch up.
This is why many people feel broke even with a decent salary. They’re trapped in a cycle of earning more but spending more. Controlling lifestyle inflation is essential. Instead of upgrading every time your paycheck grows, focus on saving, investing, or building an emergency fund. Making your money work smarter ensures your paycheck lasts and grows.
Debt Steals Your Money Before You Notice
One of the most common reasons people feel broke is debt. Loans, credit card balances, and financing arrangements can silently drain your paycheck. High-interest debt, in particular, consumes money that could otherwise go to savings or investments.
Even minimum payments can add up. If you’re not actively reducing debt, you’re essentially paying interest on money you’ve already earned. This is why some people feel broke immediately after payday. Tackling debt early and strategically is a vital step in feeling financially secure and keeping more of your money in your hands.
Psychology of Money and Instant Gratification
Feeling broke often has psychological roots. Human beings are wired for instant gratification. We want new clothes, gadgets, or experiences now, not later. This mindset can lead to overspending and emotional purchases, even when money is tight.
Learning to delay gratification—waiting, comparing prices, or planning purchases—changes your relationship with money. The longer you can resist impulsive spending, the more your paycheck lasts. Mindset shifts, like valuing financial security over temporary pleasure, are as important as any practical money strategy.
Ignoring the Power of Savings
Many people don’t save because they feel they “don’t have enough” or believe saving will reduce their quality of life. Ironically, ignoring savings is what makes them feel broke. Without an emergency fund, unexpected expenses—like medical bills, school fees, or transportation costs—can wipe out your paycheck instantly.
Even small savings make a difference. Setting aside a percentage of your income immediately after getting paid ensures your money grows. Automation tools can help by transferring a portion to savings before you even see it. Saving first, spending later, reverses the cycle of feeling broke.
Overlooking Financial Planning
Feeling broke isn’t just about spending or saving; it’s about planning. Many people live day-to-day without financial goals. Without goals, money has no direction and disappears quickly.
Financial planning includes short-term goals, like covering monthly expenses, and long-term goals, like retirement or investment growth. When your money has a purpose, every cedi earns meaning. Planning ensures you know exactly where your paycheck goes, reducing the stress of always feeling broke.
Why Mindset Matters as Much as Money
Even with budgeting and saving, mindset plays a key role. People who constantly worry about money or feel guilty about spending often feel broke regardless of income. Stress about money can lead to poor decisions—like avoiding bills, ignoring debt, or overspending on comfort items—which worsens financial health.
Building a healthy money mindset means seeing money as a tool, not a source of anxiety. It’s about discipline, perspective, and focus on growth. When you change how you think about money, your paycheck stretches naturally.
Practical Steps to Stop Feeling Broke
There are concrete actions that can immediately reduce the feeling of being broke:
-
Track every expense: Know exactly where your money goes.
-
Pay yourself first: Save before spending.
-
Cut unnecessary costs: Identify non-essential expenses and reduce them.
-
Avoid impulse spending: Delay purchases and compare options.
-
Plan for emergencies: Even a small fund prevents stress.
-
Reduce debt systematically: High-interest debt steals money fast.
-
Invest in financial literacy: Knowledge empowers smarter money decisions.
Implementing these steps creates a cycle where your paycheck lasts longer, and you feel in control rather than constantly broke.
Conclusion
Feeling broke even after getting paid isn’t a reflection of your income—it’s about how your money flows. Spending habits, debt, lifestyle choices, and money mindset all play a role. By tracking spending, prioritizing needs, saving consistently, avoiding high-interest debt, and planning for the future, you can break free from the paycheck-to-paycheck trap.
Your paycheck can become a tool for growth, not just survival. When you make intentional choices and treat money as a resource to be managed wisely, you’ll stop feeling broke and start building financial security. Remember, it’s not how much you earn but how you manage your money that determines whether it lasts.