If you’ve ever worked in a place where salary delays feel normal, then you already understand the silent stress it creates. That moment when the month is ending and your account is empty but your employer still hasn’t paid—it’s a different kind of pressure. You start calculating how long you can stretch the little you have left. You start checking your balance more often than usual. You start wondering how you will settle food, transport, electricity, data, home responsibilities, and unexpected needs. This is where money management becomes a lifeline.
Salary delay is not just a financial problem. It affects your mind, your mood, your sleep, and sometimes even your confidence. You feel stuck between responsibilities and the reality of waiting for money you already worked for. Many people in Ghana and across Africa face this situation more times than they want to admit. It’s frustrating, draining and unfair—but you still need to survive the month.
The good news is that with strong money management habits, you can cope better, avoid panic, reduce debt, and maintain control even when your income comes late. This article explores how to manage your life when salary delays become part of your reality, how to build habits that protect you, and how to plan ahead so you never feel helpless again.
Why Salary Delays Hurt So Much and How Money Management Helps
Salary delays hurt because most people plan their month around expected income. Bills don’t wait. Food doesn’t wait. Transport doesn’t wait. Life simply continues, even when your salary hasn’t arrived. This is why money management becomes essential. Without it, the month feels longer, harder, and more stressful.
One of the biggest issues with salary delay is the emotional impact. You feel anxious because you cannot control the timing of your income. You feel embarrassed when you have to explain your situation to people who depend on you. You feel frustrated when you cannot follow your plans. All these emotions affect your decision-making, and that is where money management becomes necessary—not just to survive financially, but to stay emotionally stable.
Money management helps you understand the difference between wants and needs. It forces you to prioritise and stretch what you have. It keeps you focused on survival instead of panic. It helps you make calm decisions even when your salary is taking too long. It gives you a sense of control in a situation where you normally feel powerless.
Understanding Your Current Situation Before Making Money Decisions
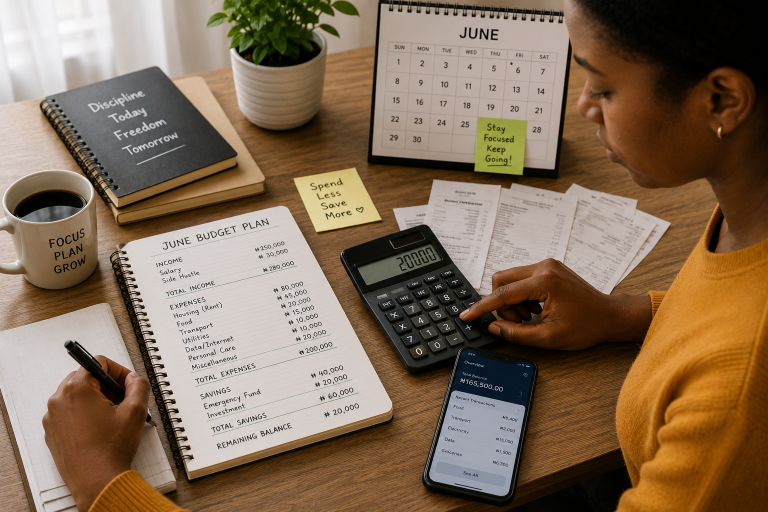
When salary is delayed, your mind naturally jumps to stress mode. You start thinking of borrowing, taking credit, asking friends for emergency help, or cutting everything at once. But the first step in good money management is clarity. You need to understand your exact situation—what you have, what you owe, what you must spend on, and what can wait.
The moment you realise the salary won’t come on time, pause and take a mental snapshot of your finances. This is where people go wrong: they panic and make rushed decisions that make things worse. Money management encourages you to face the situation with honesty. How much cash is left? Do you have mobile money? Are there pending bills? Do you have food at home? Is transport sorted? Understanding your position helps you make smart choices.
Your survival this month depends on knowing your starting point. When you’re aware of how much you have and what you must cover, you stop overspending and start planning. This is where money management begins—clarity before action.
How Daily Spending Habits Affect Your Survival When Salary Delays
Your normal spending habits determine how well you survive a salary delay. If you normally spend without tracking, the delay hits harder. If you already practise money management, the month becomes easier to navigate.
Daily habits like buying food outside, taking transport without budgeting, using data without monitoring, or doing impulse spending quietly drain your little resources. When salary delays hit, these habits hurt even more. Money management helps you become conscious of these behaviours so you can adjust quickly.
For example, if you spend 40–80 cedis a day on food, reducing that for even a week helps you stretch until the salary arrives. If you use data carelessly, small changes like using Wi-Fi or downloading offline content save money. If you take transport daily, planning routes differently reduces cost. Money management is not only about saving money—it’s about controlling habits so you don’t fall into deeper stress.
Salary delay exposes your weaknesses, but it also gives you an opportunity to build stronger money habits.
Choosing Needs First When Money Is Tight
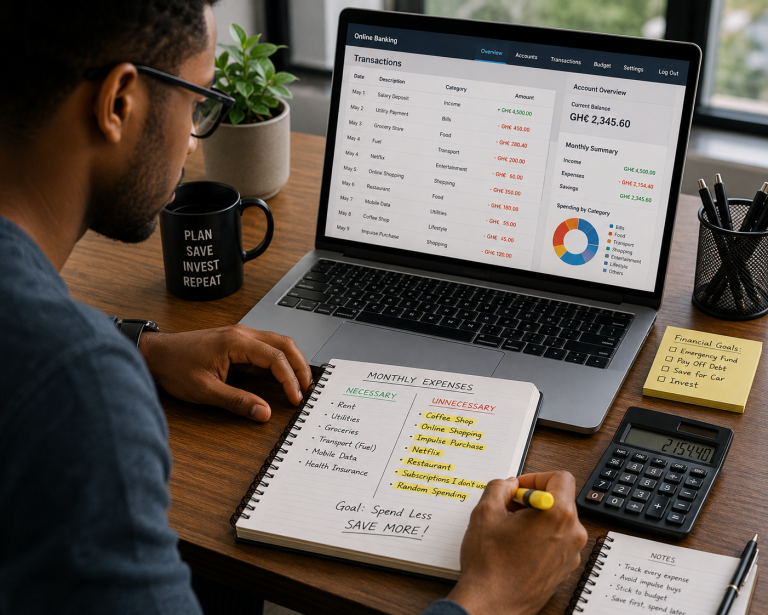
When salary is delayed, your first focus must be survival. This means prioritising needs over wants. It sounds simple, but when you’re stressed, it becomes easy to confuse the two. Needs include food, transportation, electricity, water, essential bills, and maybe school-related expenses if you have dependents. Wants are everything else that can wait.
Money management teaches you to separate these categories clearly. The moment your income delays, you stop spending like everything is normal and immediately switch into survival mode. You don’t need to feel guilty about cutting back—it’s a necessary act of self-preservation.
Needs first doesn’t mean living like you’re suffering. It means directing your limited cash towards what keeps your life stable until the salary arrives. If you treat wants as needs, the delay becomes a disaster. But when you treat needs as priority, you maintain balance even when the money is late.
This discipline becomes easier with practice. Each time you make decisions based on needs first, you strengthen your money management habits.
Managing Food, Transport and Home Expenses With Limited Cash
Food and transport consume the biggest part of daily income, so they must be managed carefully when salary delays. This is where most people either survive or fail financially.
Food is one of the easiest places to waste money, especially when you’re used to buying prepared meals. Food outside is convenient but expensive. Money management encourages cooking at home, planning portions, and using affordable ingredients to stretch what you have. Even small adjustments like eating at home before going out can save significant amounts.
Transport is also a major cost. When money is tight, you can reduce transport costs by adjusting routes, combining trips, sharing rides, or walking short distances when possible. These small changes help stretch your cash until salary comes.
Home expenses like electricity, water, and household supplies must also be managed wisely. Switching off unused appliances, avoiding unnecessary electrical consumption, and buying essentials in small but strategic quantities all help keep costs down.
The goal is not to suffer—the goal is to survive smartly. Money management helps you stretch what you have without losing dignity or comfort.
Avoiding Panic Borrowing Even When Salary Delay Tempts You
One of the biggest traps during salary delay is panic borrowing. When people panic, they borrow from everyone around them—friends, family, co-workers, or loan apps—without thinking of repayment. This creates more stress when the salary finally arrives because most of it will go back to settling debts.
Money management encourages thoughtful borrowing, not emotional borrowing. Before you borrow, ask yourself: Do I really need this money, or am I just panicking? What is the exact amount needed? Can I survive with a smaller amount? Can something wait? Borrowing smartly means borrowing only what is necessary, not what your emotions are demanding.
Loan apps especially should be avoided when possible because their fees and penalties can trap you long after the salary comes. It is better to negotiate with trusted people than to take high-interest loans.
When you manage your emotions, you manage your money better. And that is the foundation of strong money management during a salary delay.
Using Your Support System Wisely Without Feeling Ashamed
Sometimes you genuinely need help—and that is okay. Money management is not about pretending to be strong. It is about making wise decisions. If you have people you trust, you can lean on them. It could be a sibling, a close friend, or someone who understands your situation.
The key is knowing how to ask. Instead of dramatic borrowing, explain your situation honestly and specify the amount you need. Promise repayment once salary arrives and honour your promise. This helps maintain trust and prevents future embarrassment.
Support systems exist for moments like this. You don’t need to suffer alone. Money management doesn’t mean you carry every burden yourself—it means you navigate challenges smartly.
The Importance of Emergency Funds and How Salary Delays Teach You To Build One
Every time salary delays, you are reminded of why emergency funds matter. An emergency fund is simply money you save for situations where income does not come on time. It could be one week of food, two weeks of transport money, or one month of basic living expenses.
Emergency funds give you peace, confidence, and independence. They help you avoid begging, borrowing, or panicking. Building an emergency fund is part of long-term money management. You don’t need to save a huge amount at once. Small amounts saved consistently grow into a safety net.
Salary delays teach you that your financial stability should never depend entirely on your employer. When you have an emergency fund, even if salary comes late, your life stays calm. This is one of the most powerful lessons of money management.
How To Build Smarter Money Habits So Salary Delays Stop Affecting You Deeply
You cannot control when your employer pays you, but you can control how ready you are. Money management gives you the structure to survive no matter what happens. Smarter money habits include tracking your expenses, planning your month, reducing unnecessary spending, setting small savings targets, and living below your income.
These habits give you freedom. When salary delays, you are not shaken. You react with planning, not panic. You make intentional choices instead of emotional ones. You find alternatives instead of resorting to debt. You maintain your dignity.
Money management is not about suffering—it is about empowering yourself to handle life’s unpredictability.
Conclusion: Salary Delays Are Stressful, But Strong Money Management Makes You Unshakeable
Salary delay is painful. It creates fear, stress, and uncertainty. But with strong money management habits, you can survive every month with confidence. You learn to prioritise needs, adjust your lifestyle, avoid panic decisions, and maintain calm even when your income is late.
You become more intentional. You become disciplined. You become wiser with your money. And slowly, salary delays stop controlling your life. Instead of panicking, you start planning. Instead of borrowing recklessly, you make smart choices. Instead of feeling helpless, you feel prepared.
Good money management doesn’t remove salary delays—but it removes the fear attached to them. And that is the true power of financial stability.