How to create a simple monthly budget managing money can feel overwhelming, especially when expenses seem to increase every month. Many people work hard but still wonder where their money goes. By the end of the month, they find themselves struggling to save, pay bills, or reach important financial goals.
The good news is that you do not need complicated financial software or advanced accounting skills to manage your money effectively. A simple monthly budget can help you understand your income, control your spending, and make better financial decisions.
A budget is not about restricting your life or eliminating everything you enjoy. Instead, it is a plan that helps you tell your money where to go instead of wondering where it went.
Whether you are trying to save money, pay off debt, build an emergency fund, or simply gain more control over your finances, creating a monthly budget is one of the best places to start.

What Is a Monthly Budget?
A monthly budget is a financial plan that shows:
- How much money you earn
- How much money you spend
- Where your money goes
- How much you save
A budget helps you balance your income and expenses while ensuring that your financial priorities are covered.
Think of a budget as a roadmap for your money.
Without a budget, it is easy to overspend and lose track of your financial goals.
Why Budgeting Is Important
Budgeting offers several benefits.
It helps you:
- Control spending
- Reduce financial stress
- Avoid unnecessary debt
- Save consistently
- Prepare for emergencies
- Reach financial goals faster
- Make smarter financial decisions
Even a simple budget can significantly improve your financial situation over time.
Step 1: Calculate Your Monthly Income
The first step is knowing exactly how much money comes in each month.
Include all reliable income sources such as:
- Salary or wages
- Business income
- Freelance work
- Side hustles
- Rental income
- Other regular earnings
For example:
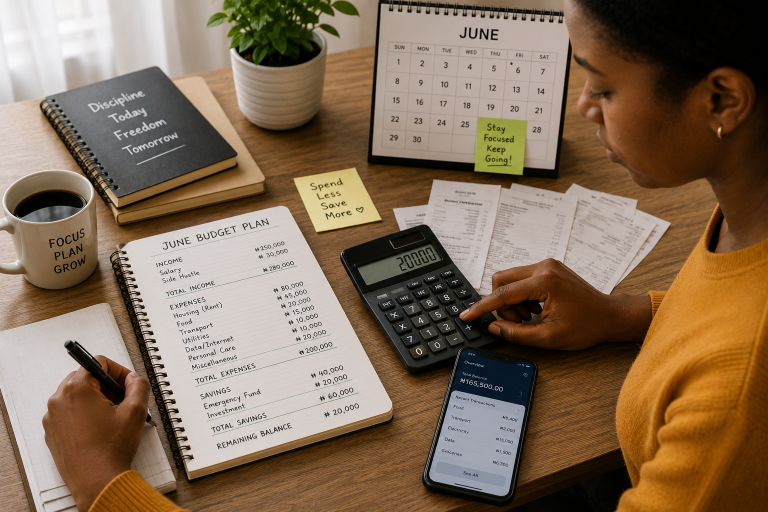
| Income Source | Amount |
|---|---|
| Salary | GHS 3,000 |
| Side Hustle | GHS 500 |
| Total Income | GHS 3,500 |
Knowing your total monthly income gives you a clear starting point for budgeting.
Step 2: List All Your Expenses
Next, write down all your monthly expenses.
Separate them into categories.
Fixed Expenses
These are expenses that remain relatively consistent each month.
Examples:
- Rent
- Loan repayments
- School fees
- Insurance
- Internet subscriptions
Variable Expenses
These expenses may change monthly.
Examples:
- Food
- Transportation
- Electricity
- Water
- Entertainment
- Personal care
Example:
| Expense | Amount |
|---|---|
| Rent | GHS 800 |
| Food | GHS 600 |
| Transportation | GHS 300 |
| Utilities | GHS 200 |
| Personal Expenses | GHS 300 |
| Total Expenses | GHS 2,200 |
Be honest and include every expense.
Small purchases can add up quickly.
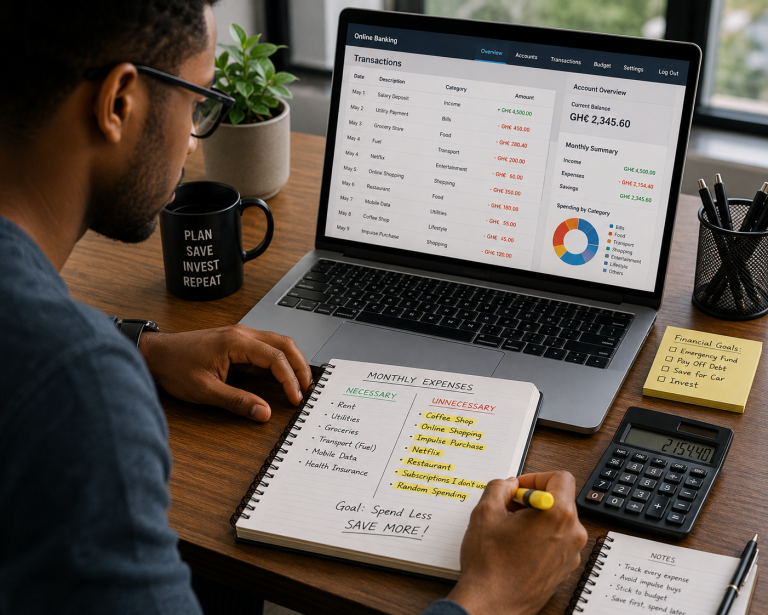
Step 3: Track Your Spending
Many people underestimate how much they spend.
For one month, track every expense.
You can use:
- A notebook
- A spreadsheet
- A budgeting app
- Notes on your phone
Tracking helps identify:
- Unnecessary spending
- Impulse purchases
- Areas where money is being wasted
The more accurate your records, the more effective your budget will be.
Step 4: Prioritize Essential Expenses

Before spending money on wants, make sure your needs are covered.
Essential expenses usually include:
- Housing
- Food
- Transportation
- Utilities
- Healthcare
- Education
- Debt payments
These should receive priority in your budget.
Step 5: Include Savings in Your Budget
One common mistake is saving only what remains at the end of the month.
Unfortunately, many people find that nothing remains.
Instead, include savings as a planned expense.
For example:
| Category | Amount |
|---|---|
| Savings | GHS 300 |
Treat savings like a bill that must be paid every month.
This approach helps build consistency.
Step 6: Use a Simple Budget Formula
A simple budgeting formula can make planning easier.
One popular approach is:
50% Needs
Essential living expenses.
30% Wants
Entertainment and lifestyle spending.
20% Savings and Debt Reduction
Savings, investments, and debt repayment.
Your percentages may vary depending on your income and responsibilities.
The goal is simply to create balance.
Step 7: Reduce Unnecessary Spending
After reviewing your expenses, look for areas where you can save money.
Examples include:
- Eating out less often
- Reducing impulse purchases
- Cancelling unused subscriptions
- Shopping with a list
- Comparing prices before buying
Small changes can create significant savings over time.
Step 8: Prepare for Unexpected Expenses
Life is unpredictable.
Unexpected costs may include:
- Medical emergencies
- Car repairs
- Home maintenance
- Family emergencies
Building an emergency fund helps protect your budget when these situations arise.
Even small contributions each month can make a difference.
Step 9: Review Your Budget Monthly
Your budget should not be created once and forgotten.
At the end of each month, review:
- What went well
- Areas where you overspent
- Opportunities to improve
- Progress toward financial goals
Regular reviews help keep your budget realistic and effective.
Common Budgeting Mistakes to Avoid
Many people struggle with budgeting because of common mistakes such as:
Not Tracking Expenses
You cannot manage what you do not measure.
Setting Unrealistic Limits
An overly strict budget can be difficult to maintain.
Ignoring Small Purchases
Small expenses often add up more than expected.
Forgetting Emergency Costs
Unexpected expenses happen.
Plan for them.
Giving Up Too Quickly
Budgeting is a skill that improves with practice.
Do not expect perfection immediately.
Sample Simple Monthly Budget
| Category | Amount (GHS) |
|---|---|
| Income | 3,500 |
| Rent | 800 |
| Food | 600 |
| Transportation | 300 |
| Utilities | 200 |
| Savings | 300 |
| Debt Payments | 300 |
| Personal Expenses | 400 |
| Emergency Fund | 200 |
| Miscellaneous | 400 |
| Total | 3,500 |
This example can be adjusted to suit individual circumstances.
Benefits of Following a Budget
When you consistently follow a budget, you may notice:
- Reduced stress
- Better spending habits
- More savings
- Less debt
- Greater financial confidence
- Improved financial security
Budgeting helps you make intentional decisions rather than reacting to financial challenges.
Final Thoughts
Creating a simple monthly budget is one of the most effective ways to improve your financial health.
You do not need expensive tools or financial expertise. What matters most is understanding your income, tracking your expenses, prioritizing your needs, and making intentional choices with your money.
Start simple. Focus on consistency rather than perfection.
Over time, small improvements in budgeting can lead to significant financial progress.
Remember that every successful financial plan begins with knowing exactly where your money is going.
A budget gives you that clarity and puts you in control of your financial future.