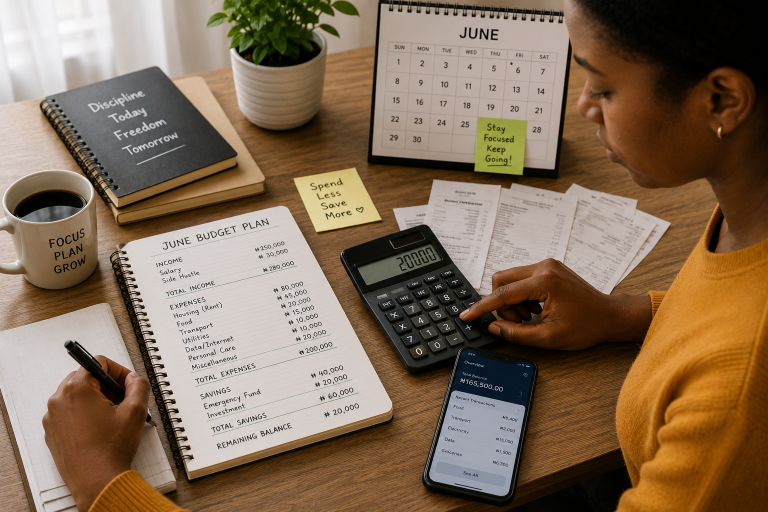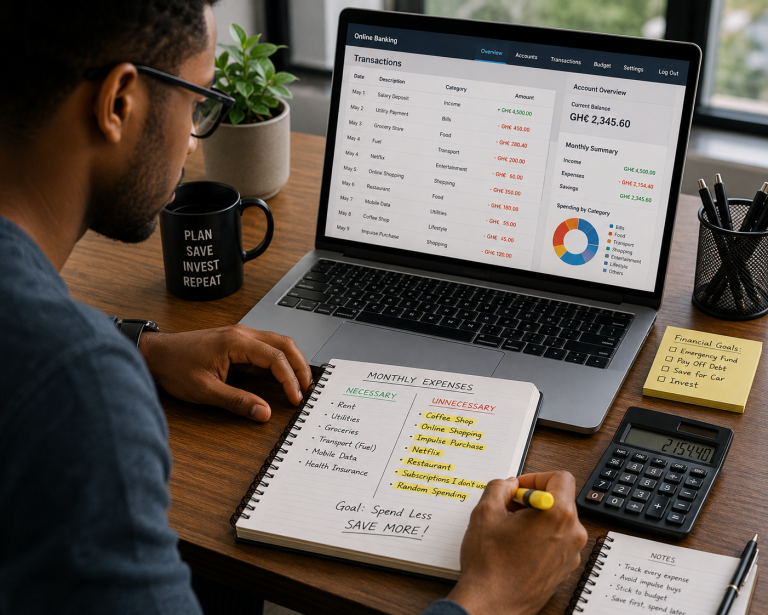
Managing money and debt as a student can be challenging, especially with the rising costs of education and the pressure to maintain a certain lifestyle. However, developing smart financial habits while in school can set you up for long-term success. Here’s a guide to help you manage your finances, avoid excessive debt, and build a solid financial foundation during your college years.
1. Create a Realistic Budget
Budgeting is the cornerstone of good financial management, especially for students. A budget helps you track your income and expenses, ensuring you live within your means. Start by listing all sources of income, such as part-time jobs, scholarships, grants, and allowances from family. Then, outline your expenses, including tuition, rent, utilities, groceries, transportation, textbooks, and entertainment.
Once you have a clear picture of your finances, allocate specific amounts for each category. Make sure your total expenses don’t exceed your income. If they do, identify areas where you can cut back. For instance, consider cooking at home instead of eating out or using public transportation instead of driving. Sticking to a budget might require discipline, but it’s a critical step in avoiding debt.
2. Understand and Manage Student Loans
Student loans can be a valuable resource for funding your education, but they also represent a significant financial responsibility. Before taking out a loan, ensure you understand the terms, including the interest rate, repayment schedule, and any fees involved. Federal student loans typically offer lower interest rates and more flexible repayment options than private loans, so prioritize these if you need to borrow.
It’s important to borrow only what you need. Avoid the temptation to take out more money than necessary, as this will increase your debt burden after graduation. If possible, make interest payments while you’re still in school to reduce the amount you owe after graduation.
3. Build an Emergency Fund
An emergency fund is a financial safety net that can help you cover unexpected expenses, such as car repairs, medical bills, or a sudden loss of income. As a student, building an emergency fund might seem challenging, but it’s an essential part of managing your finances.
Start small by setting aside a portion of your income each month, even if it’s just $10 or $20. Over time, this fund will grow, providing you with financial security and peace of mind. Ideally, your emergency fund should cover at least three to six months’ worth of living expenses.
4. Limit Credit Card Use
Credit cards can be convenient, but they can also lead to debt if not used responsibly. It’s easy to fall into the trap of spending more than you can afford, especially with high-interest rates and the temptation of minimum payments. To avoid credit card debt, use your card only for essential purchases that you can pay off in full each month.
If you already have credit card debt, focus on paying it down as quickly as possible. Prioritize payments on the card with the highest interest rate first while making minimum payments on other cards. Consider transferring your balance to a card with a lower interest rate or consolidating your debt with a personal loan to save on interest.
5. Take Advantage of Student Discounts
As a student, you have access to numerous discounts on everything from textbooks to technology to entertainment. Taking advantage of these discounts can help you save money and stretch your budget further. Always ask if a student discount is available before making a purchase.
Additionally, many companies offer special student deals on software, subscriptions, and services. For example, some streaming platforms offer discounted rates for students, while tech companies may provide discounts on laptops and software.
6. Work Part-Time or Freelance
Working part-time or freelancing while in school can provide you with extra income to cover expenses and reduce your reliance on loans. Many campuses offer part-time jobs that are flexible and designed to accommodate students’ schedules. Additionally, freelancing in areas like writing, graphic design, or tutoring can be a great way to earn money while gaining valuable experience.
Just be careful not to overextend yourself. Balancing work and school can be challenging, so make sure your job doesn’t interfere with your studies. Prioritize your education while using your job to help manage your finances.
7. Plan for the Future
It’s never too early to start planning for your financial future. While in school, take steps to build good credit by paying bills on time and managing debt responsibly. Consider opening a savings account or a retirement account, like a Roth IRA, to start building wealth early.
Financial literacy is key to long-term success, so take advantage of any financial education resources available on campus. Attend workshops, meet with a financial advisor, or take a personal finance course to learn more about managing money and preparing for life after graduation.
Smart Strategies for Passive Income: Ideas to Boost Your Financial Independence
LadaUp
Managing money and debt as a student may seem overwhelming, but with careful planning and disciplined habits, you can maintain financial stability throughout your college years. By creating a budget, understanding your student loans, building an emergency fund, and making smart financial decisions, you’ll set yourself up for a bright financial future. Remember, the habits you develop now will have a lasting impact on your financial well-being, so take control of your finances today.