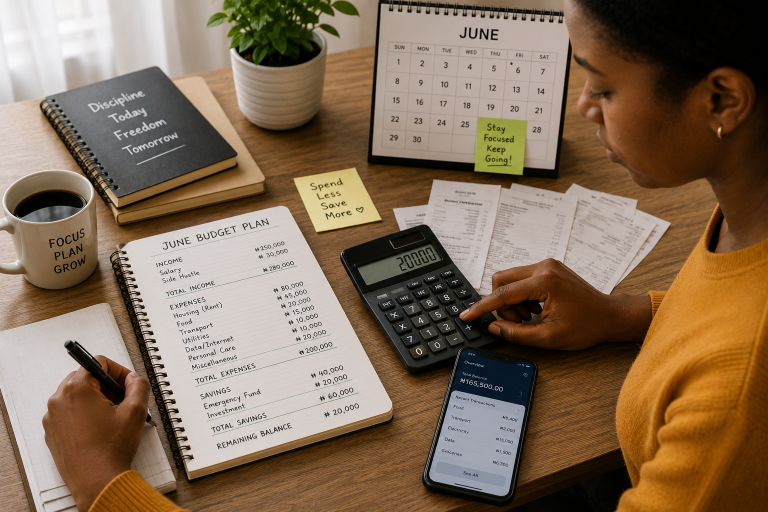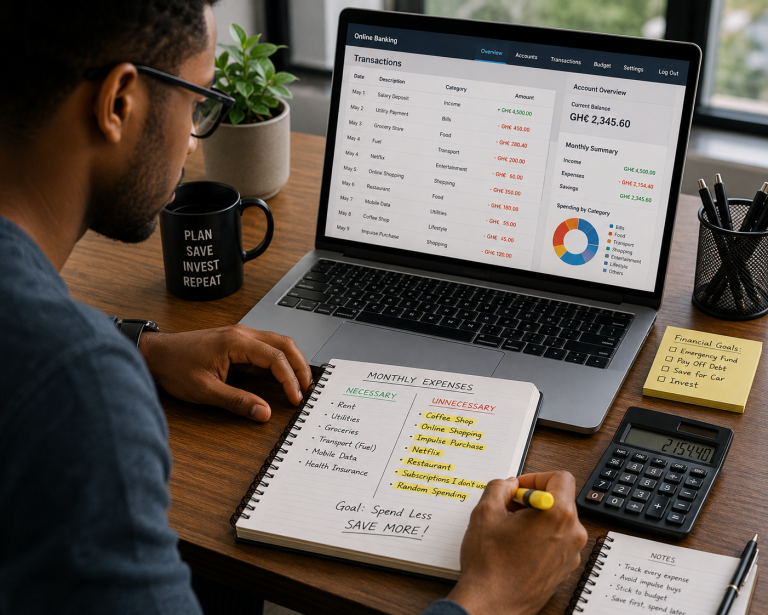
Financial freedom means being able to cover your essential expenses without constant stress — and having choices. The seven moves below focus on protecting yourself from shocks, stopping money leaks (interest), creating repeatable saving habits, and putting your money to work in ways that compound over time. Each move includes step-by-step actions, tools to use, and realistic examples so you can start today.
1) Build a true emergency fund — the safety net that keeps everything else working
Aim: 3–6 months of essential living expenses in a safe, liquid account. (Vanguard)
Why it matters
Emergencies happen: sudden medical bills, car repairs, or job loss. Without savings you lean on high-interest credit or sell investments at the worst time. A dedicated emergency fund keeps you in control.
How to build it (action steps)
- Calculate your essentials. Add rent/mortgage, utilities, food, minimum debt payments, insurance, and transport. That’s your “monthly essentials.”
- Set a target. Multiply essentials by 3 (basic) to 6 (safer). Adjust upward if you have irregular income or no job protections. (Vanguard)
- Automate a small transfer. Move $25–$200 weekly (or whatever fits) into a high-yield savings or money market account. Automation beats willpower.
- Use a separate account. Make it accessible, but not your checking account. Avoid investing this money — it must be liquid.
- Make it invulnerable. Don’t borrow from it for non-emergencies. If you must, commit to rebuilding it within a set time.
Tools & accounts
- High-yield savings accounts or no-penalty CDs (for better returns than basic checking).
- In some countries, money market accounts offer similar liquidity.
Quick example
If your essentials = $1,500/month, a 3-month fund = $4,500; a 6-month fund = $9,000. Start with a $500 “mini fund” to cover immediate small shocks while you build the rest.
2) Crush high-interest debt first — interest is the hidden tax on your future
Aim: Stop high-interest debt (credit cards, payday loans) from eating your momentum.
Why it matters
High interest compounds against you every month. Paying only minimums lets interest gobble your money and slows wealth building.
Which strategy to use? Two proven methods:
- Debt avalanche (math-first): Pay extra on the debt with the highest interest rate; this minimizes total interest paid. (Investopedia)
- Debt snowball (psych-first): Pay smallest balances first to create quick wins and momentum. Some people stick with this longer because of behavioral wins. (Investopedia)
How to choose
- If you’re disciplined and dislike paying extra interest, use avalanche.
- If you need motivation and small wins to keep going, use snowball.
Step-by-step (avalanche example)
- List debts, balances, interest rates.
- Make minimum payments on all but the highest-rate debt.
- Put any extra cash into that highest-rate balance until it’s gone.
- Roll the freed payment into the next highest rate (and repeat). (Investopedia)
Tips to accelerate
- Reallocate “fun” spending (e.g., 1–2 small luxuries) toward debt each month until you’re free.
- Consider balance transfer cards (0% intro) only if you can pay it off before the promo ends.
- Don’t add new high-interest debt while you’re paying down balances.
3) Automate savings and investing — make your future unavoidable
Aim: Make saving automatic so you don’t need willpower to build wealth.
Why it matters
Behavioral research shows automatic enrollment and precommitment dramatically raise savings rates because people stick with default actions. The “Save More Tomorrow” program is the classic example: automatic escalation tied to raises increases participation and savings over time. (UChicago Booth)
How to automate (practical steps)
- Pay yourself first. Set up automatic transfers from checking to savings and brokerage right after payday. Treat transfers like a recurring bill.
- Start small and scale. Begin at 5–10% of take-home pay. Increase the percentage yearly or when raises arrive.
- Automate investments. Use automatic contributions into retirement accounts (401(k), IRA, or country equivalent) and taxable brokerage accounts for additional investing.
- Automate debt payments too. Automatic minimums + a scheduled extra payment to reduce risk of missed due dates.
Tools & apps
- Bank auto-transfer tools, employer 401(k) automatic deferral, robo-advisors (Betterment, Wealthfront, etc.), and micro-investing apps (if it helps you start).
Example schedule
- Payday on the 1st/15th: auto-transfer $200 to emergency savings and $150 into a low-cost index fund on each payday.
4) Invest for the long run — index funds and the power of compounding
Aim: Put your excess savings into low-cost, diversified investments and hold for the long term.
Why it matters
Time in the market and low fees are the biggest drivers of investment success for most people. Low-cost index funds capture broad market returns and minimize fees that erode returns over decades. Vanguard and other firms highlight how compounding helps long-term investors overcome short-term volatility. (Vanguard)
Practical investing blueprint
- Max out tax-advantaged retirement first (where available). Employer 401(k) match is free money — capture it. Then contribute to an IRA or its equivalent.
- Prefer low-cost index funds / broad ETFs. A single total-market or S&P 500 index fund plus a bond fund is enough for most people. (Vanguard)
- Use dollar-cost averaging. Regular contributions reduce timing risk. Automate monthly buys.
- Stay diversified. Mix equities for growth and bonds/cash for stability. Rebalance once or twice a year.
- Think decades, not days. Market dips are normal; long-term investors let compounding work. (Vanguard)
Example portfolio for a beginner
- 80% total-stock market index fund, 20% total-bond index fund (adjust by age/risk tolerance). Increase bond share as you approach major goals.
Tax & account tips
- Favor tax-advantaged accounts for retirement savings; use taxable brokerage for extra investing after retirement accounts are maxed.
5) Diversify your income streams — multiple rails make you resilient
Aim: Have 1–2 extra income streams (side hustle, passive income, royalties, rental, dividends).
Why it matters
If your main paycheck stops, extra income cushions the blow, accelerates savings and gives you optionality. A large and growing share of people now supplement their incomes with side gigs—this trend is real and helpful for building wealth when done strategically. Surveys show a sizeable portion of adults have side hustles and many rely on that income for essentials or savings. (Self)
Ideas that work globally
- Skill-based freelance: writing, design, web dev, tutoring.
- Digital products: templates, mini-courses, eBooks.
- Marketplaces: selling photos, prints, or craft goods.
- Gig platforms: delivery, rideshare, task platforms (where appropriate).
- Investments that produce passive income: dividend stocks, REITs, or peer-to-peer lending (be cautious).
How to start (practical steps)
- Pick one small thing that fits your skills and time (5–10 hours/week).
- Validate it quickly: get one customer or sale before scaling.
- Reinvest initial profit into creating a better product or minor marketing.
- Aim for recurring revenue (subscriptions, repeat clients) rather than one-offs.
Warning
Not all “passive” income is passive at first—expect upfront work. Also weigh time vs reward; sometimes investing extra time into career skill growth yields higher returns than many low-pay side hustles.
6) Live below your means — design a lifestyle that scales with your goals
Aim: Maintain a gap between income and spending; invest the difference.
Why it matters
The single biggest determinant of whether you build wealth is the gap between what you earn and what you spend. It’s not how flashy your income is — it’s what you do with the surplus.
Practical rules
- Track your money. Use Mint, YNAB, or a simple spreadsheet for 30 days to see where your cash goes.
- Use a flexible budget rule. The 50/30/20 rule (50% needs / 30% wants / 20% savings) is a simple starter—adapt it to local costs and personal goals. The rule was popularized in All Your Worth by Elizabeth Warren and colleagues. (Investopedia)
- Buy big things deliberately. For large purchases, use a 24-hour rule or a 30-day waiting list to avoid impulse buys.
- Automate the difference. If your income rises, divert a portion to savings instead of inflating lifestyle.
Small habits that add up
- Cook one extra meal at home each week → save $30–$100 monthly.
- Reassess subscriptions yearly — cancel the unused ones.
- Use public transport or a fuel-efficient car where practical.
7) Learn money literacy and stay curious — the habit that multiplies everything
Aim: Spend regular time learning practical finance, taxes, and investing basics.
Why it matters
Skills compound just like money. Knowledge helps you avoid common traps, use tax-advantaged accounts well, and choose investments that make sense.
Where to start
- Books: The Psychology of Money by Morgan Housel (excellent on behavior), The Simple Path to Wealth by JL Collins (index investing primer), and All Your Worth by Elizabeth Warren (budgeting basics). (Amazon)
- Podcasts & blogs: Choose a couple of reputable sources and follow them; avoid get-rich-quick channels.
- Local rules: Learn your country’s tax rules for retirement accounts and capital gains—this changes what strategies make sense.
Simple learning habit
- 20 minutes, 3 times a week — read one chapter, listen to a 20-minute podcast, or follow a focused article. Small, steady learning beats frantic bingeing.
A realistic 12-month action plan (sample)
Use this template and adapt numbers to your situation. The goal is momentum and measurable wins.
Months 1–3: Safety and clarity
- Month 1: Calculate essentials, open high-yield savings, start $25–$100/week to emergency fund.
- Month 2: List all debts (balance, rate), pick avalanche or snowball method. Start automated repayments.
- Month 3: Set up automatic transfers for savings + retirement contributions to capture employer match.
Months 4–6: Reduce debt & habits
- Month 4: Increase debt payment by redirecting one subscription or dinner-out budget.
- Month 5: Set up one side-hustle experiment (5–10 hours/week).
- Month 6: Reassess emergency fund progress; aim for a mini-goal ($1k or one month’s essentials).
Months 7–9: Invest & scale
- Month 7: Open a taxable investment account and automate monthly contributions to an index fund.
- Month 8: Rebalance budget using the 50/30/20 rule as a guide. Increase savings rate by 1–2%.
- Month 9: Reinvest side-hustle earnings into scaling or paying down high-interest debt faster.
Months 10–12: Review and level up
- Month 10: Read a personal finance book; reassess investment allocation.
- Month 11: Evaluate side hustle: keep, pivot, or scale.
- Month 12: Celebrate wins; set the next 12-month target (e.g., 6 months emergency fund, X% invested, debt down Y%).
Common mistakes and how to avoid them
- Skipping an emergency fund and investing everything. If you need cash quickly, selling investments can lock in losses. Build a small emergency fund first.
- Chasing high returns without understanding risk. If it sounds too good to be true, it probably is.
- Letting fees eat returns. Compare expense ratios; low fees matter over decades.
- Treating side hustles like quick riches. Most start small—test before you bet big.
- Not automating. Relying on memory or motivation rarely outperforms automation.