Money has a way of slipping through our fingers if we’re not careful. One moment you feel like you’re earning enough to get by, and the next, you’re wondering where it all went. The truth is, achieving financial freedom isn’t about earning millions overnight. It’s about how you manage what you already have—and more importantly, what you avoid doing with it. Many people are unknowingly trapped by money mistakes that seem harmless at first but grow into serious barriers over time.
If you’ve ever found yourself stressed about bills, living paycheck to paycheck, or feeling stuck no matter how hard you work, you’re not alone. Most of us were never taught how to handle money properly. We learn through trial and error, often picking up bad habits that follow us for years. But the good news is that financial mistakes can be fixed. Once you recognize them and start making small but consistent changes, your path to freedom becomes much clearer.
In this article, we’ll break down the 10 most common money mistakes that hold people back from achieving financial independence. These are the traps that drain your savings, limit your opportunities, and keep you working harder instead of smarter. But by understanding them—and taking control—you can start building a future that’s not just comfortable, but truly free.
Mistake 1: Living Beyond Your Means
It’s easy to fall into this trap because it doesn’t happen all at once. You get a small raise, so you buy a slightly nicer phone. Then maybe you upgrade your car, move to a better apartment, or start eating out more often. Before you know it, your lifestyle has expanded to match your income—or worse, exceed it.
Living beyond your means is one of the biggest enemies of financial freedom. It creates an endless cycle where more money never feels like enough. The key is learning to delay gratification and spend intentionally. This doesn’t mean living miserably or denying yourself joy. It means finding a balance—spending on what truly adds value to your life while saving and investing the rest.
Financial freedom starts when your expenses are lower than your income and you use the gap wisely. When you live below your means, you create room to save, invest, and prepare for opportunities that can multiply your wealth over time.
Mistake 2: Ignoring an Emergency Fund
One unexpected event—a car breakdown, job loss, or medical bill—can throw your entire financial life off balance. Yet, many people don’t have an emergency fund. Without that safety net, even a small crisis can push you into debt, making it harder to stay on track toward financial freedom.
Building an emergency fund is one of the simplest yet most powerful steps you can take. Aim to save at least three to six months of living expenses in a separate account. It doesn’t have to happen overnight. Start small—set aside a little from every paycheck. Over time, that cushion becomes your protection from financial stress, giving you peace of mind and control when life happens.
An emergency fund isn’t just money—it’s freedom from panic. It lets you handle surprises without derailing your bigger goals.
Mistake 3: Not Tracking Where Your Money Goes
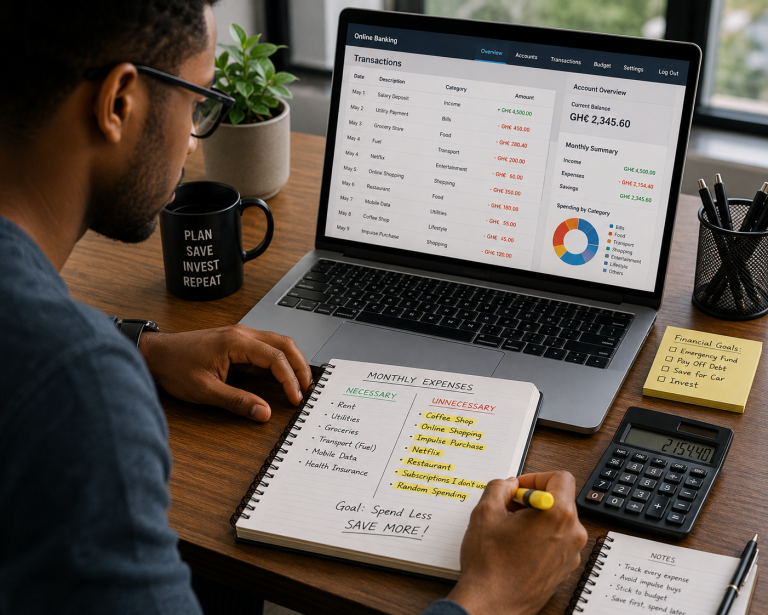
You can’t fix what you don’t measure. Yet most people have no idea how much they actually spend each month or where their money goes. This lack of awareness is one of the main reasons financial goals fail. You might think you’re spending responsibly until you see how much vanishes on takeout, subscriptions, or impulse purchases.
Tracking your expenses doesn’t have to be complicated. You can use apps like Mint, PocketGuard, or even a simple spreadsheet. The goal isn’t to feel restricted—it’s to get clarity. When you see your spending patterns clearly, you can make smarter decisions and redirect money toward things that matter, like paying off debt or building wealth.
People who achieve financial freedom don’t necessarily earn more—they manage better. And that begins with awareness.
Mistake 4: Depending on a Single Source of Income
Most people rely entirely on one paycheck to cover all their expenses. That’s risky. If that source dries up, your financial stability goes with it. In today’s unpredictable economy, having multiple income streams isn’t just smart—it’s essential.
You don’t need to start a huge business to diversify your income. It could be a side hustle, freelance work, passive investments, or even rental income. The idea is to create backup streams that support you if one fails.
Financial freedom thrives on stability. When your income comes from multiple places, you’re less vulnerable to job loss or market shifts. More importantly, it gives you the flexibility to take risks and pursue passions without fear of financial collapse.
Mistake 5: Ignoring Debt or Only Paying the Minimum
Debt can be useful if managed wisely, but it can also be a trap that steals your freedom for years. The biggest mistake people make isn’t just having debt—it’s ignoring it or paying only the bare minimum. High-interest credit cards, payday loans, and personal loans can snowball quickly, making it feel impossible to get ahead.
To achieve financial freedom, you must face your debt head-on. Start by listing what you owe, then create a plan to pay it off systematically. You can use the “debt snowball” method—paying off smaller debts first for motivation—or the “avalanche” method, targeting the highest interest rates first.
The point is to take consistent action. Every payment brings you closer to freedom. Every dollar paid toward debt is a dollar that will later work for you instead of against you.
Mistake 6: Not Investing Early Enough
One of the quietest mistakes people make is waiting too long to invest. Many think they need to be rich before they can start, but time is far more powerful than money when it comes to building wealth. The earlier you start, the more your investments can grow through compound interest—the magic that turns small, consistent contributions into significant sums.
For example, investing $100 a month starting at age 25 could grow to over $200,000 by retirement, depending on the rate of return. Waiting just 10 years to start cuts that nearly in half. That’s the cost of delay.
Even if you don’t know much about investing, you can start small with index funds, mutual funds, or retirement accounts like 401(k)s or IRAs. Learn as you go. The goal isn’t to time the market—it’s to spend time in the market.
Mistake 7: Failing to Set Clear Financial Goals
Without a clear direction, it’s easy to drift financially. You might save a little here, invest a bit there, but without specific goals, it’s hard to measure progress. Clear financial goals give your money a purpose.
Do you want to buy a home? Retire early? Travel more? Build a business? Each goal requires a plan. Write it down, break it into steps, and track your progress regularly. Having a goal keeps you motivated and helps you prioritize your spending and saving decisions.
Financial freedom doesn’t happen by accident—it’s the result of deliberate, goal-driven actions taken over time.
Mistake 8: Neglecting Financial Education
We spend years learning how to earn money but almost no time learning how to manage it. That’s why so many people make the same mistakes generation after generation. Ignorance about money is expensive—it leads to poor investment choices, unnecessary debt, and missed opportunities.
The truth is, financial education doesn’t have to be boring or complicated. You can learn from books, podcasts, online courses, or even YouTube channels dedicated to personal finance. Knowledge compounds just like money does. The more you learn, the smarter your decisions become.
Think of financial literacy as the foundation of freedom. Without it, even large incomes can be wasted. But with it, you can make confident choices that secure your future.
Mistake 9: Letting Emotions Control Financial Decisions
Money is emotional. We spend when we’re happy, stressed, or bored. We invest impulsively out of greed or panic-sell out of fear. These emotional reactions often lead to poor financial outcomes.
True financial freedom requires emotional control. Before making big purchases or investment decisions, take a step back. Ask yourself: Is this based on logic or emotion? Learning to pause before spending can save you from countless regrets.
One powerful trick is implementing a “24-hour rule.” When you want to buy something that isn’t essential, wait a day. Most of the time, the desire fades, and you realize you didn’t need it. That small habit can save you thousands over time—and keep your finances under control.
Mistake 10: Comparing Your Journey to Others
In the age of social media, comparison has become a dangerous habit. You see people flaunting vacations, cars, or success online and feel pressured to keep up. But here’s the truth: most of what you see is curated. You don’t see their credit card bills, debts, or sacrifices.
Comparing yourself to others can push you to make financial decisions that aren’t right for you. Financial freedom is deeply personal—it’s about achieving peace and security on your own terms, not trying to match someone else’s lifestyle.
Stay focused on your goals, your timeline, and your values. The real competition isn’t with others—it’s with your past self. Every step you take to improve your finances is a win.
The Path to Financial Freedom
Financial freedom doesn’t come from luck or huge paychecks—it comes from consistent, smart choices made over time. Avoiding these common money mistakes is a major part of that journey. When you stop living beyond your means, start investing early, pay off debts, and educate yourself about money, you build a foundation that grows stronger each year.
You don’t have to be perfect. The goal isn’t to never make a financial mistake again, but to learn from each one and keep improving. With every change you make—whether it’s tracking your expenses, cutting unnecessary spending, or setting up automatic savings—you move closer to a life where money is no longer a source of stress, but a tool for freedom.
Imagine waking up one day and realizing you’re not worried about bills anymore. You have choices. You can travel, pursue hobbies, or even take time off to recharge. That’s what true financial freedom feels like. And it’s achievable—not by chance, but by taking deliberate, informed action starting right now