Your credit history is one of the most important factors that determine your financial health. Whether you’re looking to buy a home, finance a car, or even rent an apartment, a positive credit history can open doors to better interest rates, loan approvals, and favorable terms. But building and maintaining a strong credit history doesn’t happen overnight—it requires careful planning, consistent habits, and a good understanding of the factors that impact your credit score.
In this article, we’ll explore key strategies for building a positive credit history and why it’s essential for your long-term financial success.
Understanding Credit History: Why It Matters
Your credit history is a record of how you’ve managed credit and debt in the past. Lenders, landlords, and even potential employers often review your credit history to assess your financial responsibility. A positive credit history can make you a more attractive borrower or tenant, while a poor or nonexistent credit history can limit your financial options.
The key components that make up your credit history include:
- Payment History: Consistently making on-time payments is the most significant factor affecting your credit score.
- Credit Utilization: This is the ratio of your credit card balances to your credit limits. Keeping your utilization low is crucial for a good credit score.
- Length of Credit History: The longer your credit accounts have been open, the more favorable it is for your credit score.
- Credit Mix: Having a variety of credit types (such as credit cards, auto loans, and mortgages) shows that you can manage different forms of credit responsibly.
- New Credit: Opening too many new credit accounts in a short period can hurt your credit score.
Now that you know what goes into your credit history, let’s look at the strategies for building a strong one.
Start with a Secured Credit Card
If you’re just beginning to build credit or have a low credit score, a secured credit card can be a great starting point. Secured credit cards require you to make a cash deposit upfront, which acts as collateral in case you fail to pay your balance. This makes them less risky for lenders, and they’re easier to qualify for than traditional credit cards.
How to Use a Secured Credit Card to Build Credit:
- Use the card for small purchases, such as groceries or gas, and pay off the balance in full each month.
- Make sure to keep your credit utilization low—ideally, below 30% of your credit limit.
- After demonstrating responsible use, you may be able to transition to an unsecured credit card.
Make Timely Payments a Priority
Payment history is the most significant factor in your credit score, accounting for about 35% of it. Making your payments on time, every time, is crucial for building a positive credit history. Even a single late payment can have a negative impact on your credit score and remain on your credit report for up to seven years.
Tips for Ensuring On-Time Payments:
- Set up automatic payments or calendar reminders to ensure you never miss a due date.
- If you’re struggling to make a payment, contact your lender as soon as possible to discuss your options. Some may offer temporary hardship programs.
Keep Your Credit Utilization Low
Credit utilization, or the amount of your available credit that you’re using, is another major factor in your credit score. A high credit utilization ratio can signal to lenders that you may be overextended and more likely to miss payments.
The general rule is to keep your credit utilization below 30%. For example, if you have a credit card with a $1,000 limit, try to keep your balance below $300 at any given time.
How to Manage Your Credit Utilization:
- Pay off your balance in full each month to avoid carrying debt.
- If you tend to carry a balance, consider making multiple payments throughout the month to keep your utilization low.
- Request a credit limit increase from your card issuer, but be cautious not to increase your spending just because you have more available credit.
Avoid Applying for Too Much Credit at Once
Each time you apply for credit, the lender performs a hard inquiry on your credit report. While a single inquiry may have a minimal impact on your score, multiple inquiries in a short period can significantly lower your score. Additionally, lenders may view multiple applications as a sign that you’re desperate for credit, which could make them less likely to approve you.
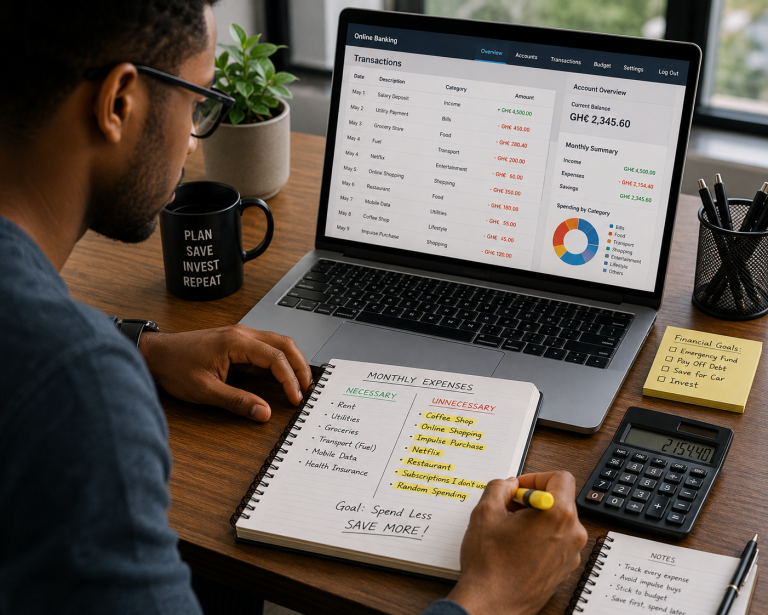
Understanding Your Spending Habits: A Step-by-Step Guide to Financial Awareness
Tips for Managing Credit Applications:
- Only apply for credit when necessary, and avoid opening too many accounts at once.
- If you’re shopping for a major loan, such as a mortgage or auto loan, try to do all your rate comparisons within a short window (typically 14-45 days). Credit scoring models will often count multiple inquiries within that period as a single inquiry.
Diversify Your Credit Mix
While it’s not essential to have multiple types of credit, having a mix of credit accounts (e.g., credit cards, installment loans, and retail accounts) can positively impact your credit score. Lenders like to see that you can manage different forms of credit responsibly.
How to Build a Diverse Credit Mix:
- If you already have a credit card, consider taking out a small personal loan or auto loan—provided you can comfortably manage the payments.
- Don’t open new accounts just for the sake of diversifying your credit mix. Only take on new debt if it makes sense for your financial situation.
Monitor Your Credit Regularly
Keeping an eye on your credit report is essential for building and maintaining a positive credit history. Regularly monitoring your credit allows you to spot any errors or potential fraud early on and address them before they cause significant damage to your credit score.
How to Monitor Your Credit:
- Request a free copy of your credit report from each of the three major credit bureaus (Equifax, Experian, and TransUnion) once a year through AnnualCreditReport.com.
- Consider signing up for a credit monitoring service that provides alerts whenever there’s a significant change to your credit report.
Conclusion: Building Credit Takes Time and Patience
Building a positive credit history is a marathon, not a sprint. It requires consistent effort, responsible financial habits, and time. By following these strategies—starting with a secured credit card, making on-time payments, keeping your credit utilization low, and monitoring your credit regularly—you can establish and maintain a strong credit history that will serve you well in the years to come