Everywhere you look, prices are rising. Groceries cost more, rent is higher, and energy bills keep increasing. Inflation and economic shifts are squeezing wallets worldwide, making it harder for people to live comfortably on the same income.
But here’s the good news: you can fight back. Saving money isn’t just about cutting back it’s about being intentional with your spending, finding creative ways to stretch your income, and building habits that protect you from financial stress.
In this guide, we’ll explore practical, relatable strategies you can use to save money when the cost of living keeps rising. These tips work no matter where you live, and they’ll help you take back control of your finances.
1. Track Every Dollar You Spend
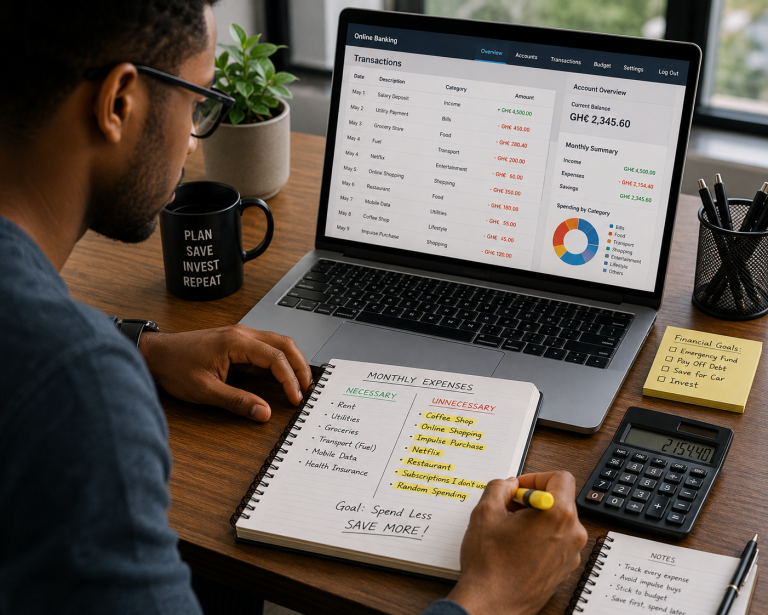
You can’t save money if you don’t know where it’s going. Most people are surprised when they see how much they spend on small, “invisible” expenses like takeout, subscriptions, or impulse shopping.
Action Step:
- Use a budgeting app like Mint, YNAB (You Need A Budget), or PocketGuard to track your spending automatically.
- If you prefer old-school, write down your expenses in a notebook for a month.
Once you see the patterns, you’ll know exactly where to cut back without feeling deprived.
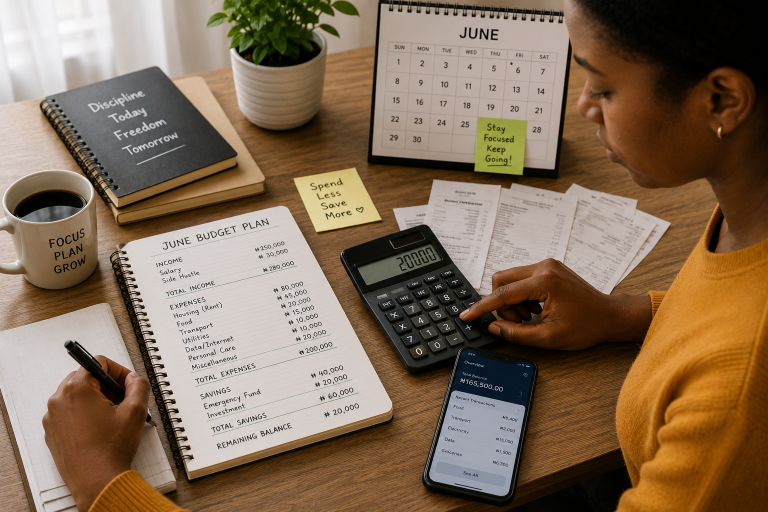
2. Build a Realistic Budget That Works
A budget isn’t about restriction it’s about freedom. A well-planned budget helps you prioritize what matters most while cutting out what doesn’t.
Simple Budgeting Methods:
- 50/30/20 Rule: 50% needs, 30% wants, 20% savings/debt.
- Zero-Based Budgeting: Every dollar gets a job (spending, saving, or investing).
Pro Tip: Automate your savings by setting up a direct transfer to a separate account the moment you get paid. That way, you’re saving without thinking.
3. Cut Back on Non-Essential Expenses

When costs rise, the fastest way to save is by trimming non-essentials. This doesn’t mean living without joy—it means being mindful.
- Cancel or pause unused subscriptions (streaming, gym, apps).
- Reduce takeout and cook more at home.
- Buy generic brands instead of premium labels.
- Use cashback apps and discount codes when shopping.
Think in terms of trade-offs: “Would I rather spend $50 on another subscription, or save it for my emergency fund?”
4. Save on Food Without Sacrificing Quality
Food is one of the biggest monthly expenses, but there are ways to eat well without overspending.
- Plan meals weekly and stick to a grocery list.
- Buy in bulk for items you use often.
- Cook in batches and freeze meals.
- Embrace affordable staples like rice, beans, oats, and frozen vegetables.
- Avoid shopping when hungry it leads to impulse buys.
5. Lower Your Housing Costs
Housing is often the largest expense. While you can’t always change your rent or mortgage overnight, there are ways to reduce costs.
- Negotiate your rent landlords often prefer a stable tenant over vacancy.
- Consider downsizing if you’re paying for space you don’t use.
- House-hack: Rent out a room or list your space on short-term rental platforms.
- Energy efficiency: Simple changes like LED bulbs, unplugging electronics, and sealing leaks can cut utility bills.
6. Smarter Transportation Choices
Gas, insurance, and car maintenance add up quickly. Consider alternatives:
- Use public transportation when possible.
- Carpool with colleagues or friends.
- Walk or bike for short trips it saves money and improves health.
- If you must drive, keep up with regular maintenance to avoid costly breakdowns.
7. Build an Emergency Fund
Rising costs often come with financial surprises. An emergency fund protects you from turning to debt when life happens.
Goal: Save at least 3–6 months’ worth of essential expenses in a separate account. Start small if you must—even $10 a week adds up over time.
8. Reduce Debt to Free Up Cash
Debt eats into your income, making it harder to keep up with rising expenses.
Strategies to Pay It Off Faster:
- Snowball Method: Pay off the smallest debt first, then roll payments into the next one.
- Avalanche Method: Focus on debts with the highest interest rate first.
- Refinance or consolidate loans for lower interest.
Each payment you eliminate is money back in your pocket every month.
9. Look for Ways to Increase Your Income

Sometimes, cutting expenses isn’t enough you need to earn more. Luckily, the digital world has opened endless opportunities.
- Freelancing (writing, design, virtual assistance, coding).
- Online tutoring or teaching.
- Selling products or services through platforms like Etsy, Fiverr, or Upwork.
- Remote jobs in customer service, marketing, or tech.
- Monetize your hobbies like photography, crafts, baking, or blogging.Even a few hundred extra dollars a month can make a big difference.
10. Embrace a Simpler Lifestyle
One of the most powerful money-saving strategies is redefining what “enough” means for you. Rising costs can push us into chasing more money, but sometimes the real solution is spending less and appreciating what we already have.
- Practice minimalism: declutter and sell unused items.
- Choose experiences over things.
- Focus on long-term happiness, not short-term pleasure.
Conclusion
The rising cost of living is a global challenge, but it doesn’t have to control your life. By tracking your spending, budgeting wisely, cutting unnecessary costs, and looking for ways to boost your income, you can stay financially stable even when prices keep climbing.
Remember, saving money isn’t about living with less—it’s about creating a life where money supports your goals, instead of holding you back. Start small, stay consistent, and watch your financial confidence grow.