If someone has ever told you, “You can’t save because you don’t earn enough,” chances are you believed them. Many people think saving money is only for those with big salaries, steady jobs, or extra income at the end of the month. If you are earning little, paying bills feels like survival already, so saving sounds unrealistic, almost insulting.
But here’s the honest truth. Saving with little income is not only possible, it is often more important than saving with a lot of money. When income is small, every decision matters more. Every habit shows faster results. And every small step compounds into something meaningful over time.
This article is not about extreme sacrifice or pretending money problems don’t exist. It’s about learning how to work with what you have, not against it. It’s about understanding how saving really works and how everyday people with limited income quietly build financial stability.
If you’ve ever said, “I’ll start saving when I earn more,” this article is for you.
Why Saving Feels Impossible When Income Is Small
When income is low, the pressure is real. Rent, food, transport, family needs, emergencies, and social obligations compete for attention. At the end of the month, there is often nothing left. So saving feels like a luxury.
But the problem is not always income alone. Often, it is the way money flows without structure. When money has no direction, it disappears quickly, no matter how much or how little comes in.
Saving with little income becomes possible when you shift from reacting to expenses to planning around them. The goal is not to save a lot. The goal is to save consistently.
Consistency matters more than amount.
The Real Meaning of Saving
Saving is not about hoarding money or denying yourself joy. Saving is about giving your future self options. It is about creating breathing space so that one emergency does not destroy months of effort.
When income is small, savings protect you from panic. They reduce stress. They give you confidence. Even a small savings balance can change how you think and act.
Saving with little income starts with understanding that saving is a habit first, not a number.
Why Waiting to Earn More Delays Everything
Many people postpone saving until their income increases. The logic sounds reasonable. But the habit you build now is the habit you carry into higher income.
If you don’t save when income is small, chances are you won’t save when income grows. Expenses grow with income. Lifestyle expands quietly. The opportunity to save disappears again.
People who save early, even in small amounts, find it easier to save more later. They already have the mindset and discipline.
This is why learning how to start saving with little income matters so much.
Understanding Your Money Without Fear
One reason saving feels hard is because many people avoid looking closely at their money. They are afraid of what they’ll see. But avoiding numbers does not improve them.
You don’t need complex budgets or financial apps to understand your money. You just need honesty. Knowing how much comes in and how much goes out gives you control.
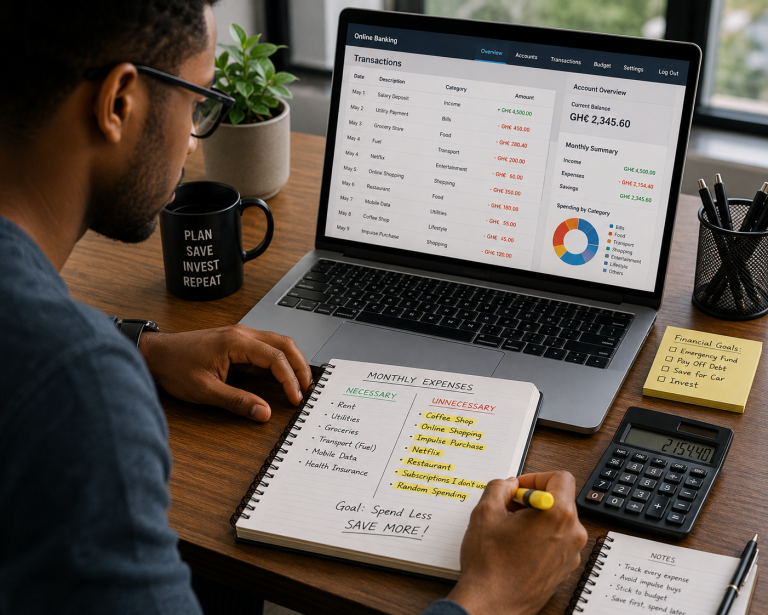
When you understand your spending patterns, you begin to notice leaks. Small daily expenses that feel harmless but add up over time. This awareness alone often creates room for saving.
Saving with little income begins with awareness, not restriction.
Small Amounts Still Matter
One of the biggest lies about saving is that small amounts are useless. In reality, small savings are powerful because they build the habit and confidence.
Saving the equivalent of a cup of tea a day may not sound impressive, but over months it becomes meaningful. More importantly, it proves to you that saving is possible.
Psychology matters here. When you see yourself as someone who saves, your behavior changes naturally.
The Power of Paying Yourself First
When money comes in, most people pay everyone else first. Bills, family, transport, subscriptions, and impulse spending all take priority. If anything remains, they save. Usually, nothing remains.
Paying yourself first flips this order. You save a small amount immediately when income arrives. Even if it’s tiny, it comes first.
This method works because it removes decision fatigue. You don’t negotiate with yourself later. You treat saving like a non-negotiable expense.
Saving with little income works best when saving is automatic and intentional.
Making Saving Invisible
Saving becomes easier when it’s not constantly tempting you. If money stays in your main account or wallet, you’ll find reasons to spend it.
Separating savings from daily spending reduces temptation. Whether it’s a savings account, mobile money wallet, or trusted cooperative, distance helps.
When saving feels invisible, it becomes effortless.
Learning to Say No Without Guilt
One of the biggest challenges for people with low income is social pressure. Friends, family, and cultural expectations often demand spending beyond your capacity.
Saving with little income requires boundaries. Saying no does not mean you don’t care. It means you are protecting your future.
This can feel uncomfortable at first, especially if you are used to pleasing others. But financial stability grows when you respect your limits.
Over time, people adjust to your boundaries.
Emotional Spending and How It Affects Saving
Money is emotional. Stress, boredom, frustration, and comparison drive spending decisions. When income is small, emotional spending hurts more.
Positive saving habits start with recognizing emotional triggers. When you spend to feel better temporarily, you often feel worse later.
Saving with little income improves when you find healthier ways to cope with emotions. Talking, resting, walking, or learning something new costs little but saves a lot.
Building an Emergency Buffer Slowly
Emergencies are one of the biggest reasons people fall into debt. When income is low, emergencies feel catastrophic.
Even a small emergency fund changes everything. It turns chaos into inconvenience.
You don’t need a large target at the beginning. Focus on building something, not everything. Each small deposit strengthens your financial resilience.
Income Is Small But Control Is Powerful
You may not control how much you earn right now, but you control how you respond to it. Saving is an act of self-respect. It tells your future self, “I didn’t forget about you.”
Saving with little income builds discipline, patience, and confidence. These qualities affect more than money. They influence how you approach life.
Saving While Supporting Others
Many people support family members or dependents. This makes saving harder but not impossible. The key is honesty and communication.
You don’t have to explain every detail of your finances, but you can set limits. Supporting others should not mean destroying yourself.
Saving with little income while supporting others requires balance, not guilt.
Avoiding Debt That Steals Your Future
High-interest debt is one of the biggest enemies of saving. It consumes future income before you even receive it.
When income is small, avoiding unnecessary debt becomes critical. Debt removes your ability to save later.
Saving, even in small amounts, reduces dependence on borrowing.
Why Consistency Beats Motivation
Motivation comes and goes. Consistency builds results. You don’t need to feel inspired to save. You need systems that work even when you’re tired.
Saving with little income improves when saving becomes routine, not emotional.
Small actions done repeatedly outperform big actions done once.
How Saving Changes Your Mindset
As savings grow, even slowly, your mindset shifts. You feel calmer. You make better decisions. You stop living only for today.
This mental shift often leads to better opportunities. You think longer-term. You take smarter risks.
Saving changes how you see yourself.
Long-Term Benefits of Saving Early
People who save early, even with little income, develop financial confidence faster. They are better prepared for opportunities, emergencies, and growth.
Saving is not just about money. It’s about freedom. Freedom to say no. Freedom to choose. Freedom to breathe.
Saving with little income plants the seed for financial independence.
Final Thoughts
Starting to save with little income is not easy, but it is absolutely possible. It does not require perfection, big numbers, or sudden sacrifice. It requires intention, patience, and honesty.
The goal is not to save fast. The goal is to save consistently. Even small steps matter.
Your income does not define your discipline. Your starting point does not define your future. Saving begins the moment you decide to care for tomorrow.