Saving sounds easy on paper. You earn money, you keep some, and you spend the rest. Yet almost every adult experiences the same struggle: they want to save, but somehow the money disappears. Bills pull from one side, responsibilities pull from another, emergencies never stop showing up, and life always seems to demand just a little more than your income can stretch. Before you know it, saving becomes a dream rather than a routine. People feel guilty about not saving enough, ashamed when they look at their accounts, and frustrated because they know saving is important but can’t figure out how to make it work.
But the truth is this: most people don’t fail to save because they’re irresponsible. They fail because saving requires systems, habits, and structure — things we were never really taught in school. Financial literacy is still shockingly low around the world. The Global Financial Literacy Survey shows that only 33% of adults actually understand basic financial principles, which means most people have been left to simply “figure out” saving on their own. And when you don’t have the right tools, even your best intentions collapse.
This article dives deep into why people fail at saving and how to fix it in a practical, realistic way. Whether you’re a student, a young professional, a parent, or a business owner, you’ll find yourself here. Saving is not magic. Saving is a habit. And once you build it, everything changes — your confidence, your peace of mind, your stability, and your future.
The Real Reason Saving Is So Hard for Most People
The first truth about saving is simple: saving is emotional, not mathematical. Of course, money involves numbers, but your behavior around money is driven by habits, beliefs, and triggers. People spend because they’re stressed, they’re happy, they’re sad, they’re bored, or because they’re trying to feel in control. You may have every intention to save, but the moment stress hits, your saving plan becomes a distant memory.
Another major problem is that people treat saving like an optional activity rather than a non-negotiable responsibility. Rent, bills, school fees, transportation — these all get paid automatically because they have immediate consequences. Saving, however, feels like something you can postpone. You tell yourself you’ll save next month because this month is tough. But next month brings new problems. So saving gets pushed aside over and over again.
There is also the issue of lifestyle inflation. When income increases, spending usually increases even faster. People start saving less because they start believing they “deserve” more comfort as they earn more. And yes, comfort is good. But when comfort replaces discipline, saving collapses.
Finally, many people fail to save because they rely on willpower. But willpower is not strong. Willpower is inconsistent. Anything can shake it — emotions, stress, surprises, a simple impulse decision. Saving requires systems, not strength.
The Psychology Behind Poor Saving Habits
Your relationship with saving is shaped by your upbringing, your environment, and your mindset. If you grew up in a home where saving was never discussed, it becomes hard to adopt the habit naturally. If you grew up seeing money used for emergencies only, saving may feel stressful or pointless. If your background taught you that money comes to fix problems, your brain may link money to stress instead of opportunity.
Even culture plays a role. In many communities, you are expected to support family members, contribute to events, or handle responsibilities beyond yourself. Saving becomes difficult when you feel pressure to help everyone. And while generosity is wonderful, it should never replace your personal security.
Another psychological barrier is the reward system in your brain. Buying something gives you an instant dopamine boost, while saving offers no immediate pleasure. Saving feels like sacrifice. Spending feels like reward. Your brain will always chase the easier reward unless you train it differently.
But the good news? These patterns can be changed. Anyone can learn to save. Anyone can build discipline. Anyone can develop a healthier relationship with money. You simply need a saving strategy that works with your behavior rather than against it.
Why Most Saving Plans Fail Before They Even Start
The biggest mistake people make is setting a saving goal without understanding their spending behavior. For example, someone may say, “I’ll save 40% of my salary every month” without calculating their expenses. Or they may decide to save a fixed amount that isn’t realistic. This creates frustration because the plan collapses before it gains momentum.
Most saving plans also fail because people save after spending, instead of before spending. If saving is not the first thing you do when money enters your account, you will never save consistently. Life will always find a way to take the money first.
Another common issue is not having a clear purpose for the saving. Saving for “the future” is too vague. Saving for “emergencies, business startup, travel, rent cushion, or investment capital” gives the brain clarity and motivation.
People also fail because they rely on memory instead of automation. If you need to manually remember to transfer money each month, you’ll skip it when you’re stressed, tired, busy, or emotionally down. Automation removes the pressure.
And finally, there is the habit of waiting for the “perfect time.” Many people say, “I’ll start saving when I earn more.” But saving begins with discipline, not income. You train your mind to save with what you have now so that when more money comes, your saving behavior already exists.
Why Saving Must Become a Lifestyle, Not a Temporary Project
Saving becomes successful only when it becomes part of your identity. When you see yourself as a saver, you naturally make better decisions. You say no to unnecessary expenses. You ask yourself questions before buying things. You choose stability over impulse.
But this shift happens gradually. You don’t wake up one day and suddenly become disciplined. You build discipline through small commitments. You start with saving a small percentage, even if it’s just 5%. You build the habit first, then increase the amount.
Once saving becomes part of your lifestyle, it becomes automatic. You don’t force yourself. You don’t argue with yourself. You simply save because that’s who you are now. This mindset is what separates people who save consistently from people who struggle.
The Real Cost of Not Saving
When you don’t save, you live in constant financial tension. Every emergency becomes a crisis. Every unexpected bill becomes a problem. Your peace disappears because you have no backup. You start depending on loans, friends, or credit. You make emotional financial decisions because there is no cushion protecting you.
The long-term cost is even worse. Without saving, you can’t invest. Without saving, you can’t start a business. Without saving, you stay in jobs you don’t like because you can’t afford to take risks. Without saving, you can’t grow wealth.
Saving is the foundation of freedom. Saving is the first step to breaking financial stress. Saving is the key to unlocking opportunities. And until saving becomes a priority, financial progress will always feel slow.
How to Finally Build a Saving Habit That Works
The first solution is to adopt the principle of paying yourself first. This means saving immediately when money enters your account — not after expenses. Even if you start with a small amount, this simple change transforms everything. It signals to your brain that saving is important.
You also need a realistic saving percentage based on your income and responsibilities. Saving 10% is a good starting point for most people. Once it becomes easy, increase it to 15%, then 20%, then more. The key is consistency, not size.
Next, make saving automatic. If possible, set up a standing order that moves money from your main account to a separate saving account instantly. When the process is automatic, your emotions don’t interfere.
Separate your savings into different purposes. When your brain knows you’re saving for something clear — emergency fund, business, rent cushion, long-term goals — it becomes easier to stay motivated.
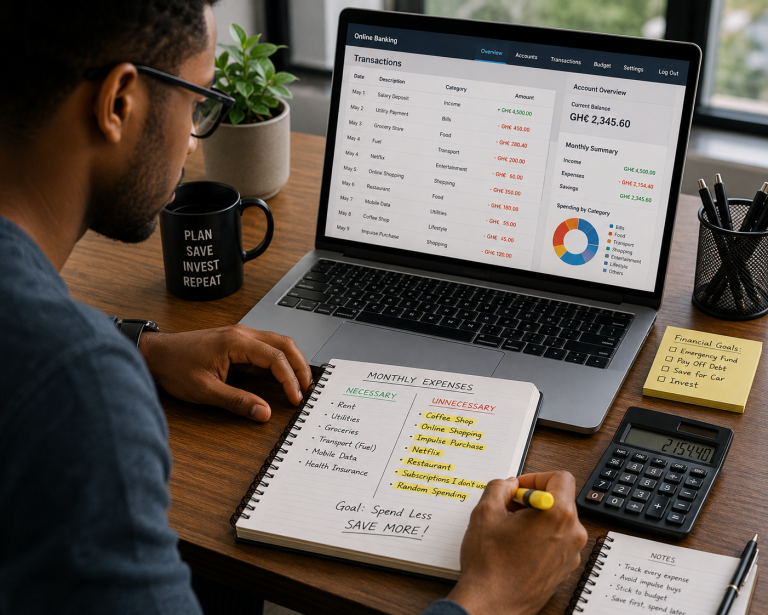
Another crucial step is to reduce financial leaks. These are the small, unnoticed expenses that slowly drain your money — daily snacks, impulse purchases, extra data bundles, entertainment subscriptions, unnecessary outings. Once you track these leaks, you’ll be shocked at how much you can save simply by removing what you don’t need.
Finally, protect your savings. Don’t touch it unless it’s for the exact purpose you set. If you regularly remove money from your savings, your brain stops taking the habit seriously. Guard your savings the way you guard your rent money.
Building Emergency Savings to Protect Your Future
One of the most powerful forms of saving is building an emergency fund. This is money saved specifically to protect you from life’s surprises — broken electronics, medical bills, unexpected travel, job loss, car issues, or family emergencies.
Experts recommend saving at least three to six months of living expenses, but you don’t have to achieve this overnight. Start small. Even a one-month buffer can reduce stress dramatically. As your income grows, increase your emergency savings until you feel secure.
Emergency savings prevent debt. Emergency savings protect your peace. Emergency savings give you confidence. This one habit alone can transform your financial life.
Why Your Mindset Determines Your Saving Success
Saving begins and ends in the mind. If you believe saving is painful, you’ll always struggle. If you believe saving is restricting, you’ll avoid it. But if you train your mind to see saving as freedom, security, and peace, everything becomes easier.
A strong saving mindset understands that discipline now creates comfort later. It understands that saying “no” to spending today is saying “yes” to a better future. It sees the long-term picture, not just the moment.
When you change your mindset, you change your saving habits. And when you change your saving habits, you change your entire financial life.
Why Small Savings Matter More Than Big Ones
Many people don’t save because they think their small income isn’t enough. But wealth is built through consistency, not size. Saving $1 every day is better than saving $100 once and giving up. Small savings build discipline. Small savings train your brain. Small savings create momentum.
Over time, small savings grow. They multiply through interest. They accumulate into opportunities. They create stability. And most importantly, they turn saving into a natural habit.
Never underestimate the power of small steps. They build big futures.
Conclusion: A New Beginning for Your Saving Journey
Saving is not about being rich. Saving is about being responsible with your future. Saving gives you freedom, confidence, and peace. Saving opens doors that spending can never open. Saving protects you from stress, pressure, and emergencies. Saving is one of the greatest gifts you can give to yourself.
Most people fail to save because they don’t have a system, a mindset, or a structure that supports the habit. But now you do. You know what causes the struggle. You know what needs to be fixed. You know how to create a lifestyle where saving becomes effortless.
Start small. Stay consistent. Build discipline. Protect your peace. And remember this: saving is not just money you keep. Saving is your future in your hands.